




 Why do we ask?


Tip: Check your credit card statement each month to confirm you recognize all charges. If you have multiple credit cards, check each statement individually.
Has your personal data been recently exposed?
Check if information like your Social Security number, email, and passwords is exposed on the dark web.

You have reached the maximum number of scans allowed. Please come back after 24 hours.

Scanning the dark web...
Scanning public databases...
Scanning millions of records...
Narrowing down the search...
We need more information
Please enter a few more details to ensure we show you the right information.
Risk level:
High
You’re at high risk
We found your personal information on the dark web and on data broker sites.
Your personalized protection plan
Product Benefits:
 Up to $3M Reimbursement for identity theft, with up to $1M for Stolen Funds†††
$10K Scam Reimbursement7
Scam Support
Credit, Checking and Savings Activity Alerts: Unlimited Accounts
Credit & Payday Loan Lock2
Credit Monitoring:
3 Bureau1
Automatic Data Broker Removal8
Dark Web Monitoring
Priority 24/7 Customer Phone Support
LifeLock Total
Your price:
$
349.99
Your price:
$
34.99
60-day money back guarantee with an annual plan
24/7 Live Member Support
No one can prevent all cybercrime or prevent all identity theft.
- Price valid for introductory term. After that, your price will renew at the standard price.
- Your subscription begins immediately after your transaction is complete. A payment method is required at sign-up for trials, and you will be charged at the end of your trial, unless canceled first.
- Prices are subject to change and may be charged up to 35 days prior to renewal. Cancel here or contact Member Services.
- Restrictions apply. Automatically renewing subscription required. If you're a victim of identity theft and not satisfied with our resolution, you may receive a refund for the current term of your subscription. See lifelock.norton.com/guarantee for complete details.
††† Up to $1 million coverage for Lawyers and Experts included with all plans. Reimbursement and expense compensation vary according to plan. Insurance benefits are issued by third parties. See lifelock.norton.com/legal for policy info.
1 Bureau Monitoring and Monthly Credit Report and Score / 3 Bureau Monitoring and Monthly Credit Report and Score.
2 Credit Lock cannot prevent all account takeovers, unauthorized account openings, or credit file inquiries. Deactivates if you downgrade or cancel your subscription.
7 Scam protection coverage as part of identity theft benefits is currently available to all customers residing in the United States, including U.S. territories and the District of Columbia, with the exception of residents of New York. Gen Digital is not a licensed insurance producer. Benefits under the Master Policy are issued and covered by HSB Specialty Insurance Company. You can find further details and exclusions in the summary of benefits.
8 After setup, automatic data broker removal service scans and requests removal every 90 days.
Risk level:
Medium
You’re at medium risk
We found your personal information on data broker sites.
Your personalized protection plan
Product Benefits:
Up to $1.2M Reimbursement for identity theft, with up to $100K for Stolen Funds†††
$5K Scam Reimbursement7
Scam Support
Credit, Checking and Savings Activity Alerts:
5 Accounts
Credit & Payday Loan Lock2
Credit Monitoring:
3 Bureau1
Automatic Data Broker Removal8
Dark Web Monitoring
Priority 24/7 Customer Phone Support
LifeLock Advanced
Your price:
$
199.99
Your price:
$
19.99
60-day money back guarantee with an annual plan
24/7 Live Member Support
No one can prevent all cybercrime or prevent all identity theft.
- Price valid for introductory term. After that, your price will renew at the standard price.
- Your subscription begins immediately after your transaction is complete. A payment method is required at sign-up for trials, and you will be charged at the end of your trial, unless canceled first.
- Prices are subject to change and may be charged up to 35 days prior to renewal. Cancel here or contact Member Services.
- Restrictions apply. Automatically renewing subscription required. If you're a victim of identity theft and not satisfied with our resolution, you may receive a refund for the current term of your subscription. See lifelock.norton.com/guarantee for complete details.
††† Up to $1 million coverage for Lawyers and Experts included with all plans. Reimbursement and expense compensation vary according to plan. Insurance benefits are issued by third parties. See lifelock.norton.com/legal for policy info.
1 Bureau Monitoring and Monthly Credit Report and Score / 3 Bureau Monitoring and Monthly Credit Report and Score.
2 Credit Lock cannot prevent all account takeovers, unauthorized account openings, or credit file inquiries. Deactivates if you downgrade or cancel your subscription.
7 Scam protection coverage as part of identity theft benefits is currently available to all customers residing in the United States, including U.S. territories and the District of Columbia, with the exception of residents of New York. Gen Digital is not a licensed insurance producer. Benefits under the Master Policy are issued and covered by HSB Specialty Insurance Company. You can find further details and exclusions in the summary of benefits.
8 After setup, automatic data broker removal service scans and requests removal every 90 days.
Risk level:
Low
Good news!
We didn’t find your personal information across millions of records or on public data sources.
Your personalized protection plan
Product Benefits:
Up to $1.05M Reimbursement for identity theft, with up to $25K for Stolen Funds†††
Identity Restoration Specialists
Credit, Checking and Savings Activity Alerts:
2 Accounts
Credit & Payday Loan Lock2
Credit Monitoring:
2 Bureau1
Automatic Data Broker Removal8
Dark Web Monitoring
Breach Alerts
24/7 Customer Phone Support
Lifelock Core
Your price:
$
124.99
Your price:
$
12.49
60-day money back guarantee with an annual plan
24/7 Live Member Support
No one can prevent all cybercrime or prevent all identity theft.
- Price valid for introductory term. After that, your price will renew at the standard price.
- Your subscription begins immediately after your transaction is complete. A payment method is required at sign-up for trials, and you will be charged at the end of your trial, unless canceled first.
- Prices are subject to change and may be charged up to 35 days prior to renewal. Cancel here or contact Member Services.
- Restrictions apply. Automatically renewing subscription required. If you're a victim of identity theft and not satisfied with our resolution, you may receive a refund for the current term of your subscription. See lifelock.norton.com/guarantee for complete details.
††† Up to $1 million coverage for Lawyers and Experts included with all plans. Reimbursement and expense compensation vary according to plan. Insurance benefits are issued by third parties. See lifelock.norton.com/legal for policy info.
1 Credit features require successful setup, identity verification, and sufficient credit history by the appropriate credit bureau. Credit monitoring features may take several days to activate after enrollment.
2 Identity Lock cannot prevent all account takeovers, unauthorized account openings, or credit file inquiries. Deactivates if you downgrade or cancel your subscription.
8 After setup, automatic data broker removal service scans and requests removal every 90 days.
1/2
Finding your match...

DID YOU KNOW?
10 cents
If your information is exposed or stolen in a data breach, it can end up on the dark web where it can be sold for as little as 10 cents.
100M+
LifeLock monitors hundreds of millions of data points a second.
Based on your concerns, the best plan for you is:
LifeLock Core
(Individual)
LifeLock Advanced
(Individual)
LifeLock Total
(Individual)
LifeLock Core
(2 adults)
LifeLock Advanced
(2 adults)
LifeLock Total
(2 adults)
LifeLock Core
(2 adults + up to 10 kids)
LifeLock Advanced
(2 adults + up to 10 kids)
LifeLock Total
(2 adults + up to 10 kids)
Pricing details below*
Pricing details below*
Pricing details below*
Pricing details below*
Pricing details below*
Pricing details below*
Pricing details below*
Pricing details below*
Pricing details below*
- Up to $1.05M Reimbursement for identity theft, with up to $25K for Stolen Funds†††
- Up to $1.2M Reimbursement for identity theft, with up to $100K for Stolen Funds†††
- Up to $3M Reimbursement for identity theft, with up to $1M for Stolen Funds†††
- Up to $1.05M Reimbursement for identity theft, with up to $25K for Stolen Funds††† for each adult
- Up to $1.2M Reimbursement for identity theft, with up to $100K for Stolen Funds††† for each adult
- Up to $3M Reimbursement for identity theft, with up to $1M for Stolen Funds††† for each adult
- Up to $1.05M Reimbursement for identity theft, with up to $25K for Stolen Funds††† for each adult
- Up to $1.2M Reimbursement for identity theft, with up to $100K for Stolen Funds††† for each adult
- Up to $3M Reimbursement for identity theft, with up to $1M for Stolen Funds††† for each adult
- Credit Monitoring Coverage1
- Credit Monitoring1 each adult
- Credit Monitoring1 for family
- Credit, Checking & Savings Account Activity Alerts
- Credit, Checking and Savings Activity Alerts for each adult
- Credit, Checking and Savings Activity Alerts for family
- 401K & Investment Account Activity Alerts
- 401K/Investment Account Alerts for each adult
- 401K/Investment Account Alerts for family
- Recurring and Unusual Charge Alerts
- Unexpected & Suspicious Charge Alerts for each adult
- Unexpected & Suspicious Charge Alerts for family
- Stolen Funds Reimbursement†††
- Stolen Funds Reimbursement††† for each adult
- Stolen Funds Reimbursement††† for family
- Lawyers and Experts†††
- Lawyers & Experts††† for each adult
- Lawyers & Experts††† for family
- Automatic Data Broker Removal8
- Automatic Data Broker Removal8 for each adult
- Automatic Data Broker Removal8 for family
- Scam Reimbursement7
- Scam Reimbursement7 for each adult
- Scam Reimbursement7 for family
- Credit Reports & Scores1
- Credit Report & Score for each adult
- Credit Report & Score for family
- Social Media Monitoring
- Social Media Monitoring for each adult
- Social Media Monitoring for family

We have more plans to choose from.
See all plans

Have questions?
Contact sales
*Your subscription begins immediately after payment and automatically renews unless cancelled. Discount for annual plans are compared to monthly billing. Prices subject to change and may be charged up to 35 days before current term ends. Cancel here or contact Member Services.
††† Up to $1 million coverage for Lawyers and Experts included with all plans. Reimbursement and expense compensation vary according to plan. Insurance benefits are issued by third parties. See LifeLock.Norton.com/legal for policy info.
1 Credit features require successful setup, identity verification and sufficient credit history by the appropriate credit bureau. Credit monitoring features may take several days to activate after enrollment.
7 Scam protection coverage as part of identity theft benefits is currently available to all customers residing in the United States, including U.S. territories and the District of Columbia, with the exception of residents of New York. Gen Digital is not a licensed insurance producer. Benefits under the Master Policy are issued and covered by HSB Specialty Insurance Company. You can find further details and exclusions in the Summary of Benefits.
8 After setup, automatic data broker removal service scans and requests removal every 90 days.
Why do we ask?
Identifying your concerns gives us the ability to recommend the right plan for your needs.
Return to quiz
Why do we ask?
Knowing this number helps us recommend coverage that fits your needs.
Return to quiz
Why do we ask?
Providing your email address makes you eligible for notifications of potential identity threats.
Return to quiz
How to dispute a credit card charge in 4 steps
Ever noticed a suspicious purchase on your credit card that you don't remember making? You can dispute the unauthorized credit card charge directly through the merchant or with your credit card company. Learn more about disputing credit card charges, then subscribe to LifeLock for help detecting and recovering from credit card fraud.
Unauthorized credit charges can occur after data leaks, physical card theft, card skimming, and in plenty of other ways — some of which are impossible to prevent. According to the FTC, credit card fraud was the most reported form of identity theft in 2023, and victims lost nearly $250 million throughout the year. Thankfully, there’s a straightforward process for disputing unauthorized credit charges when they pop up in your statements.
Here’s how to dispute a credit card charge:
1. Review your purchase history
Look over your recent purchase history for any transactions you don’t recognize, and don’t ignore the small charges. Credit card thieves sometimes use carding schemes, which involve charging your card for a very small amount to validate that it’s active — and sometimes to ensure you’re not paying attention to your history. Make a record of any fraudulent charges.
Check your pending charges, too. You can’t dispute charges that are pending, because the amount might change or get removed from your account, but once the charge has officially been made, you can begin the dispute process immediately.
2. Determine who to contact first
Once you've identified a suspicious charge, determine whether you should first contact the merchant who filed the charge or your credit card issuer. If the charge is for a purchase you made but the amount is wrong, or you’re unhappy with the product or service, contact the merchant directly.
It’s best to reach out to the merchant directly in the following situations:
- You received poor quality or damaged goods.
- You were dissatisfied with the service.
- You were sent the wrong item or service.
- You canceled an order but were still charged.
- You returned an item but haven't received a refund.
- There was an error in how you were billed.
Conduct a quick online search of unfamiliar business names listed on your credit card statement. Many businesses operate under different names or outsource their billing and finance departments, so the charge could be legitimate but listed under a name you don’t recognize.
It’s best to reach out to the credit card company directly in the following situations when you think a charge is fraudulent:
- The location of the charge doesn’t match your recent purchases or travel history.
- The charge is for an unusually large or out-of-pattern amount.
- You notice charges from a merchant you haven’t done business with.
Be sure to check with other authorized users on your account to see if they made the purchase. If you still can’t identify the charge, it may be credit card fraud, and you should contact your credit card company immediately.
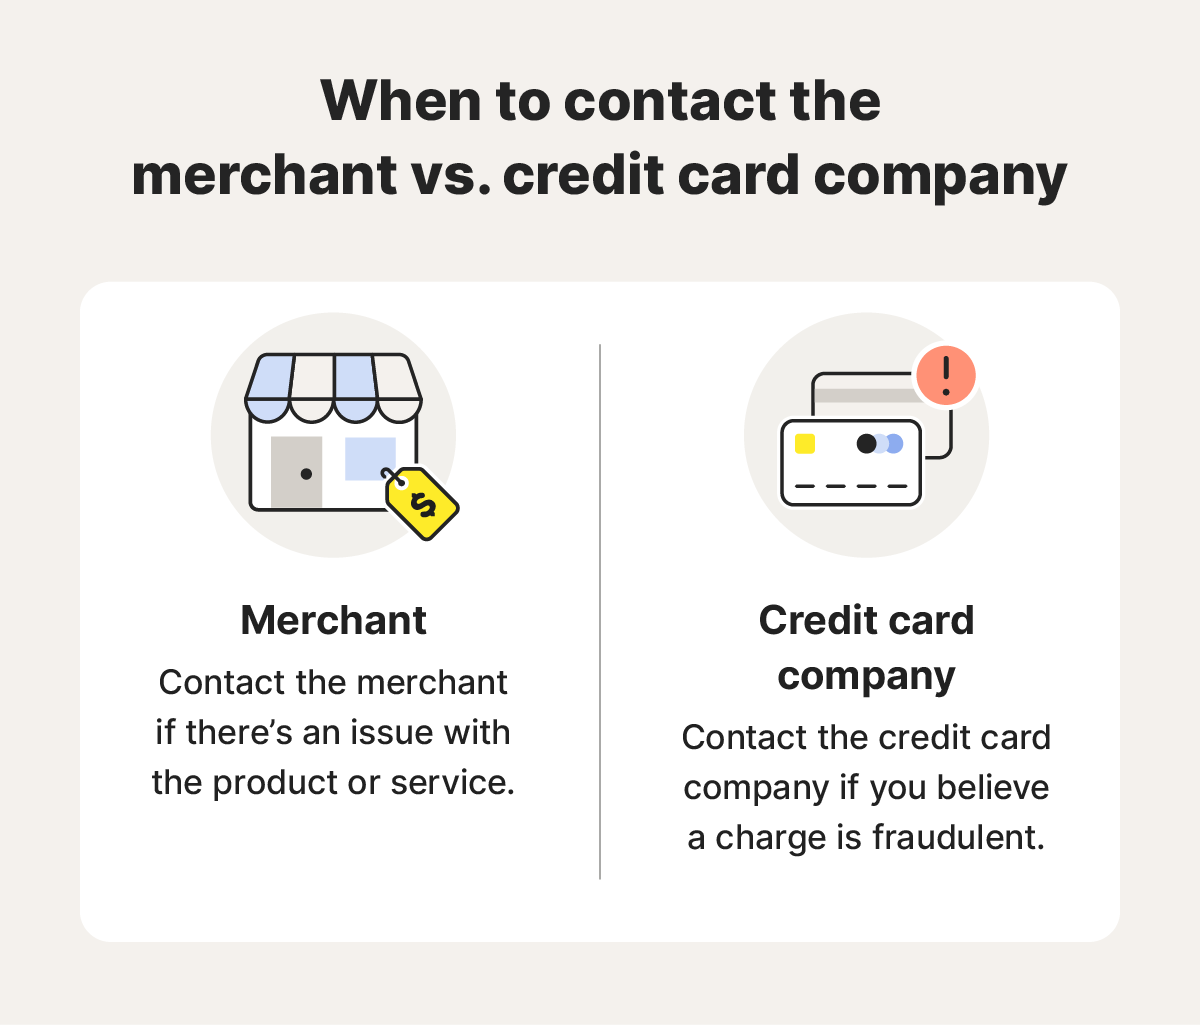
A graphic explaining when to contact a merchant about a credit card charge vs when to file a claim with a credit card company.
3. Contact the merchant
If you’ve determined that contacting the merchant is the best next step, look for their contact information on your credit card billing statement or receipt. If you plan to dispute an incorrect amount charged to your card, you’ll need to provide the proof you collected when you reviewed your purchase history. You’ll also want to find the receipt for the item or service to prove the discrepancy.
If the merchant refuses to handle the dispute, doesn’t want to issue a refund, or you believe the charges were fraudulent, file a dispute with your credit card issuer.
4. File a dispute with your credit card company
If you suspect a charge is fraudulent or a merchant won’t issue a refund, dispute it with your credit card company directly so they can request a chargeback. You can usually do this by phone, online, app, or mail depending on your credit card provider.
The Fair Credit Billing Act allows you to withhold payment on the disputed amount while the charge is being investigated, which typically takes up to 90 days.
How long do you have to dispute a credit card charge?
According to the Fair Credit Billing Act, you have 60 days from the statement date to dispute a charge. However, you should review your credit card issuer’s specific policies since some offer a longer window or have additional requirements to dispute charges.
How long does a dispute take to resolve?
After you file a dispute, your card issuer has 30 days to acknowledge it and must complete the investigation within two billing cycles — usually up to 90 days. While the dispute is being reviewed, you aren’t required to pay the disputed charge, but you should continue paying the rest of your bill.
How to protect yourself from fraudulent credit card charges
Receiving a damaged item or lackluster service from a business is annoying, but it's not nearly as alarming as finding out an unauthorized person has your credit card number. Fortunately, there are steps you can take to better protect your personal information and minimize the chances of someone accessing your credit card information.
- Invest in identity theft protection tools: LifeLock monitors millions of internet data points per second and notifies you if your personal information appears in fraudulent credit applications or other unsavory places.
- Use strong passwords: Skip easy-to-guess passwords like your pet’s name or birthday. Use long, strong, and unique passwords, and get a password manager to help generate and store them.
- Enable two-factor authentication: Two-factor authentication helps you stay secure online by requiring you to verify your identity in a way others can't duplicate. This helps prevent cybercriminals from accessing your financial accounts, even if they have your password.
- Check your credit card statement monthly: Review every purchase on your credit card statement monthly to ensure all charges are accurate. If you notice a strange transaction, you’ll have plenty of time to dispute it with the appropriate party.
- Opt for contactless payment: Contactless forms of payment — such as chip cards or digital wallets — help reduce credit card skimming and card cloning. They’re also encrypted forms of payment, meaning that even if data is intercepted, it can’t easily be used to commit credit card fraud.
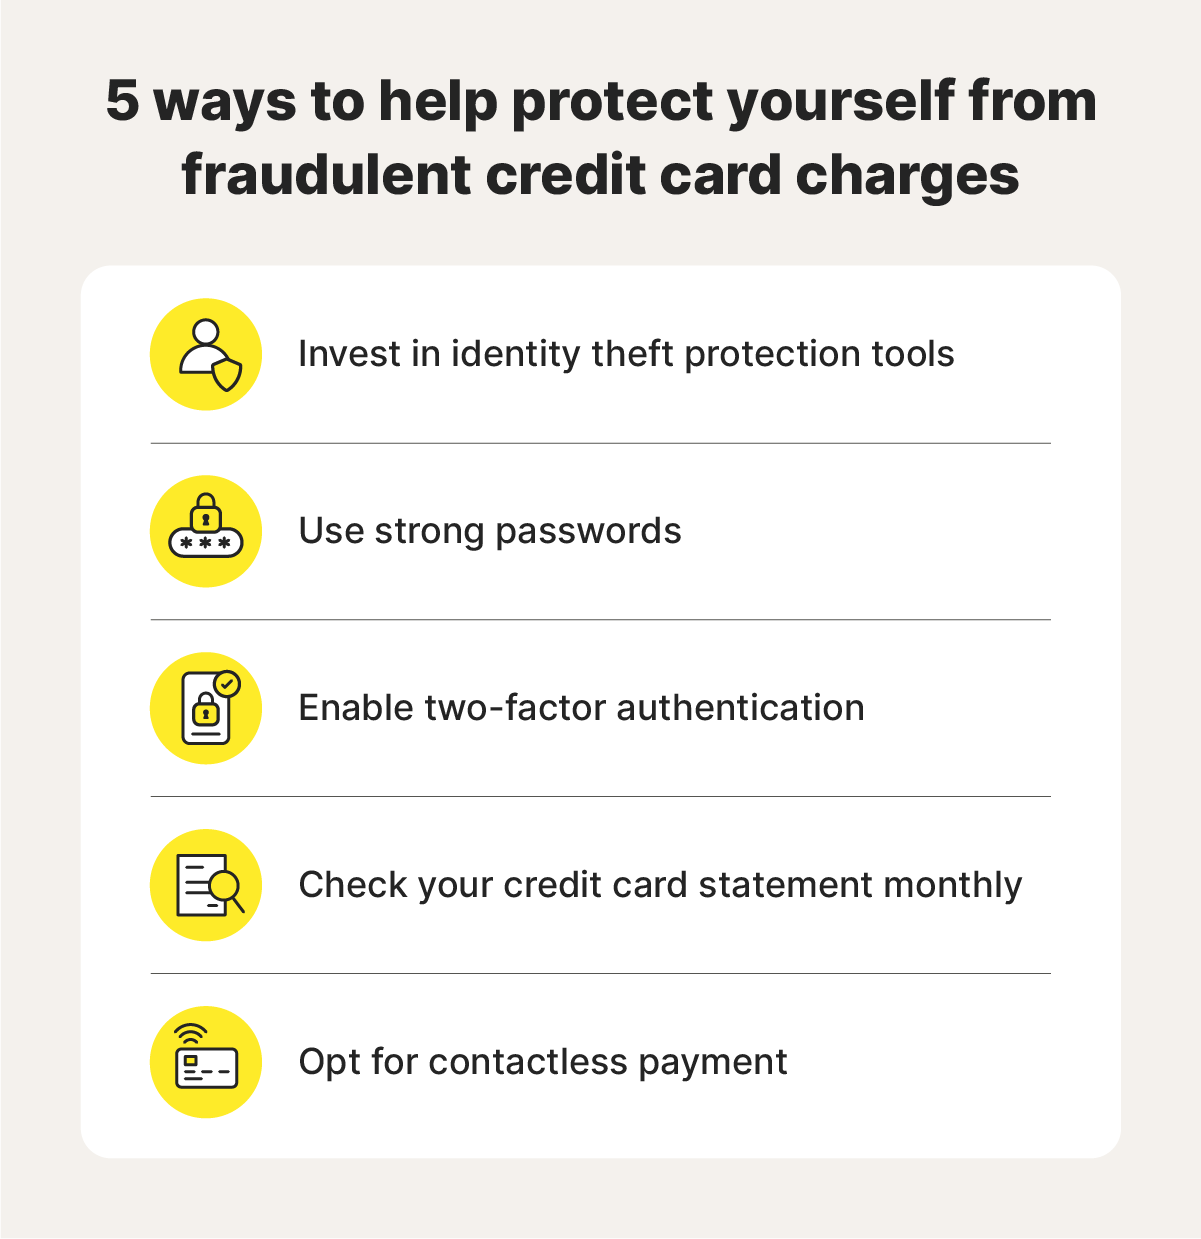
Graphic providing 5 strategies to protect yourself from credit card fraud.
Help protect your credit with LifeLock
LifeLock Advanced provides added protection from credit card fraud by alerting you if we detect potentially unauthorized credit card applications and purchases.* By taking a more proactive approach to monitoring your credit and personal information, you can help protect yourself and your credit against fraud.
FAQs
Can I dispute a credit card charge I willingly paid for?
It depends. If you paid for an item or service of poor quality, you can contact the merchant to dispute the charge. However, if you willingly made a purchase that you don’t plan to return or are satisfied with, you cannot dispute that charge. Attempting to file a dispute for a purchase you knowingly made to get a refund is known as friendly fraud and is considered unethical.
Who pays when you dispute a charge?
If the dispute is resolved in your favor, the charge will be removed, and you won’t need to pay anything; in such cases, it’s typically the merchant who ends up paying. If the dispute is not resolved in your favor, you must pay the charge.
What happens if your credit card dispute is denied?
Your credit card company will explain why the dispute was denied, and you will likely be responsible for paying the charge.
*LifeLock does not monitor all transactions at all businesses.
Editors’ note: Our articles provide educational information about identity theft, scams, financial fraud, and other topics that can put your identity or personal accounts at risk. LifeLock offerings may not cover or protect against every type of crime, fraud, scam, or threat we write about. For more details about how we write, review, and update our articles, see our Editorial Policy.
This article contains
- 1. Review your purchase history
- 2. Determine who to contact first
- 3. Contact the merchant
- 4. File a dispute with your credit card company
- How long do you have to dispute a credit card charge?
- How long does a dispute take to resolve?
- How to protect yourself from fraudulent credit card charges
- Help protect your credit with LifeLock
- FAQs
Related articles
Credit & Finance
How to dispute credit report errors and get them removed
August 25, 2026
·
8 min read
Credit & Finance
How to dispute credit report errors and get them removed
August 25, 2026
·
8 min read
Credit & Finance
How to dispute credit report errors and get them removed
August 25, 2026
·
8 min read